Transferring money from Germany to the UK is quite easy once you understand how it works. The key is to do it safely and avoid paying high fees.
I’ve put together this page to explain everything you need to know in plain English.
Wanting to send money to Germany? Click through for information and guidance on that transfer!
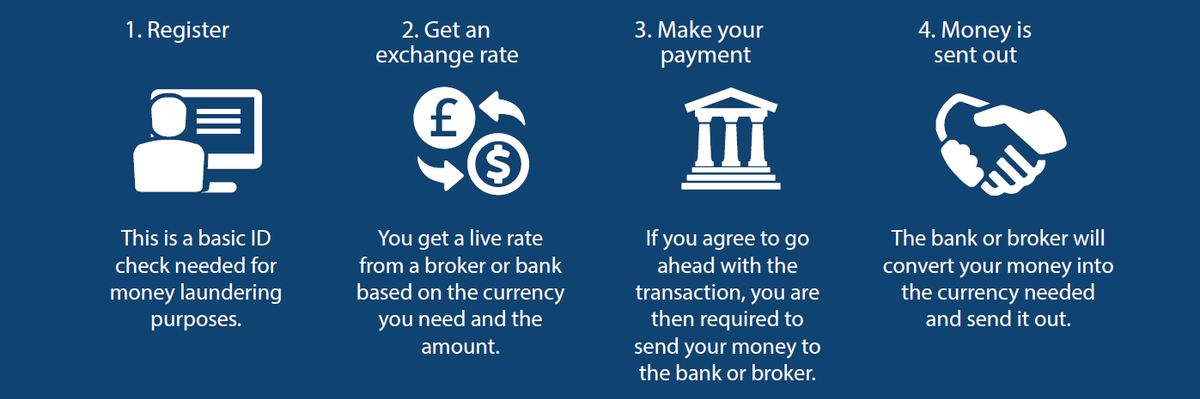
How to transfer money from Germany to the UK
Step 1 – Identity check
For new customers, an ID check is required by financial regulations. Existing customers can skip this step.
Most people can be verified using their passport number and address. This is generally a fast, painless process.
Step 2 – Lock in an exchange rate
The Euro (EUR) to Pound Sterling (GBP) rate changes every few seconds. Our EUR to GBP converter shows this, with consistent live updates!
A bank or money transfer specialist will provide you with their latest rates.
If you are happy to go ahead, the exchange rate is locked in, and you will be emailed a confirmation with all the details of your transaction.
Step 3 – Send in your Euros
Before any money is converted, you need to send in your Euros to pay for your money transfer.
Your email confirmation will include the bank details of where to send your money. This is done using a normal domestic bank transfer (online or in a branch).
Step 4 – Your Euros are converted into Pounds
Once your Euros have been received, your bank or money transfer company will convert them into Pounds and send them to the UK bank account you have requested.
That’s it!
Usually, the whole thing is quick and painless.
The best way to transfer money from Germany to the UK
When you want to send money overseas, it can seem like you have endless options.
But it comes down to this:
You can use a bank or a money transfer company.
The best way to transfer money from Germany to the UK is a trade-off between cost and convenience.
Money transfer companies are generally better for larger transfers due to lower costs. Banks may be better for small payments as you can utilise your existing bank account.
There are pros and cons to each, which you can see below.
Pros | Cons | Best for | |
|---|---|---|---|
Bank | Can use your existing account | High charges, minimal help, daily limits | Small payments, convenience |
Money Transfer Specialist | Normally lower cost | Need to register first | Large or regular amounts (over €5,000) |
Costs Compared: Banks vs. Money Transfer Companies
Whenever you transfer money from Germany to the UK there are two charges to watch out for:
- Transfer fees
- Exchange rates
The transfer fee is the more visible cost; however, the exchange rate is the more important cost.
1. Transfer fees
Transfer fees are a flat fee charged every time you make an international transfer.
While the big banks tend to charge them, some money transfer companies don’t charge any transfer fees.
Here’s what two of the big German banks charge:
Deutsche Bank: €11.55 minimum or 0.15% of the total amount.
Commerzbank: €12, €25, or €75 depending on the amount you send.
The big UK banks typically charge around £15 to £25 per transfer.
I should point out that the transfer fees are in addition to the exchange rate costs.
If you want to avoid paying any transfer fees, use a money transfer specialist (at Key Currency we charge you no transfer fees).
2. Exchange Rates
Every bank and money transfer company has its own exchange rates.
Each provider will have a markup or margin on top of their wholesale costs. The exchange rate margin can vary considerably.
And because exchange rates are moving around throughout the day, it can make comparisons difficult.
As a general piece of advice, I’ve found banks are not very competitive when it comes to exchange rates.
The margins charged by banks are sometimes so fat they only change their rates a few times a day.
I guess a lot of people just assume they have no choice in the matter and use their bank by default.
Something to note – both banks and money transfer specialists offer tighter margins for larger amounts (it’s the way of the world I’m afraid). There is not a single rate for all amounts.
As a simple suggestion, get a quote from a money transfer specialist and compare the overall cost.
You don’t need to build a spreadsheet or use a complex formula.
Just find out how what your Euro amount will give you in Pounds net of all fees. Write it down and compare. The biggest number wins.
Make sure you carry out any exchange rate comparison at roughly the same time.
You want to be comparing apples with apples.

How to get the best exchange rate
As I explained before, achieving a favourable exchange rate is the most important part of sending money from Germany to the UK.
Getting the best exchange rate is easier said than done in the real world.
That’s because exchange rates are in a constant state of change.
The larger your transfer, the more sensitive it will be to movements in the Euro to Pound rate.
For example, if you were transferring say €50,000, even a tiny 1% adverse swing in the exchange rate could cost you an extra €500.
Daily moves of 1% happen all the time.
Sometimes over a week, you can see 2%-3% fluctuations.
Those daily 1% moves, and the 2% to 3% swings over a week, are easier to see on a live chart than in a single quoted rate.
EUR to GBP rate = 0.83714953
This data uses the mid-market rate. For an exchange rate on your money transfer, please get a transfer quote.
Use the buttons to see whether today’s euro to pound rate looks better or worse than it has over the past day, month, or year.
Unless you plan to watch exchange rates all day long, you might find it easier for a money transfer specialist to help you with timing.
Some money transfer specialists, such as Key Currency, assign every customer an account manager.
An account managers is watching the screens all day anyway as part of their job. They will be more familiar with the prevailing trends, volatility, and trading ranges.
I should point out that banks and many money transfer specialists don’t offer this kind of bespoke service.
For example, there is an increasing number of online-only operators, such as PayPal, TransferWise, and Revolut, which offer “do-it-yourself” platforms or apps.
They essentially provide you with a platform and leave you to it. It’s up to you to enter all the information and decide when it’s the right time.
They tend to be more popular for smaller amounts (under €5k), where the rate has less of an impact.
However, from my experience, people who are looking to transfer larger amounts feel nervous about having to do everything themselves.
They would prefer having the peace of mind of speaking to someone that can offer expertise and a helping hand.
If you mess up the timing of your transfer, it could cost you a lot of money.
On a £75,000 transfer, squeezing an extra 0.5% out of the rate will put an extra £375 in your pocket.
For both individuals and businesses, that is money you don’t want to give away.
Receiving some guidance on exchange rates could ultimately significantly reduce your costs.
Can you trust online exchange rates?
We all rely on the internet these days for a lot of the information we use.
The same goes for exchange rates.
Many websites provide free exchange rates to the public.
Some of the more popular sites are XE, Oanda, DailyFX, and X-Rates.
For those looking to send money, it is deceiving not having a real rate as it can affect your plans and budgeting.
My suggestion is you get a quote from an actual provider (bank or money transfer company).
At least that way you will know what your money is worth and can then plan effectively.